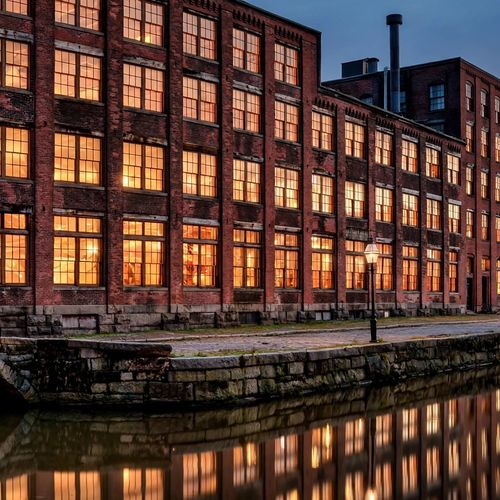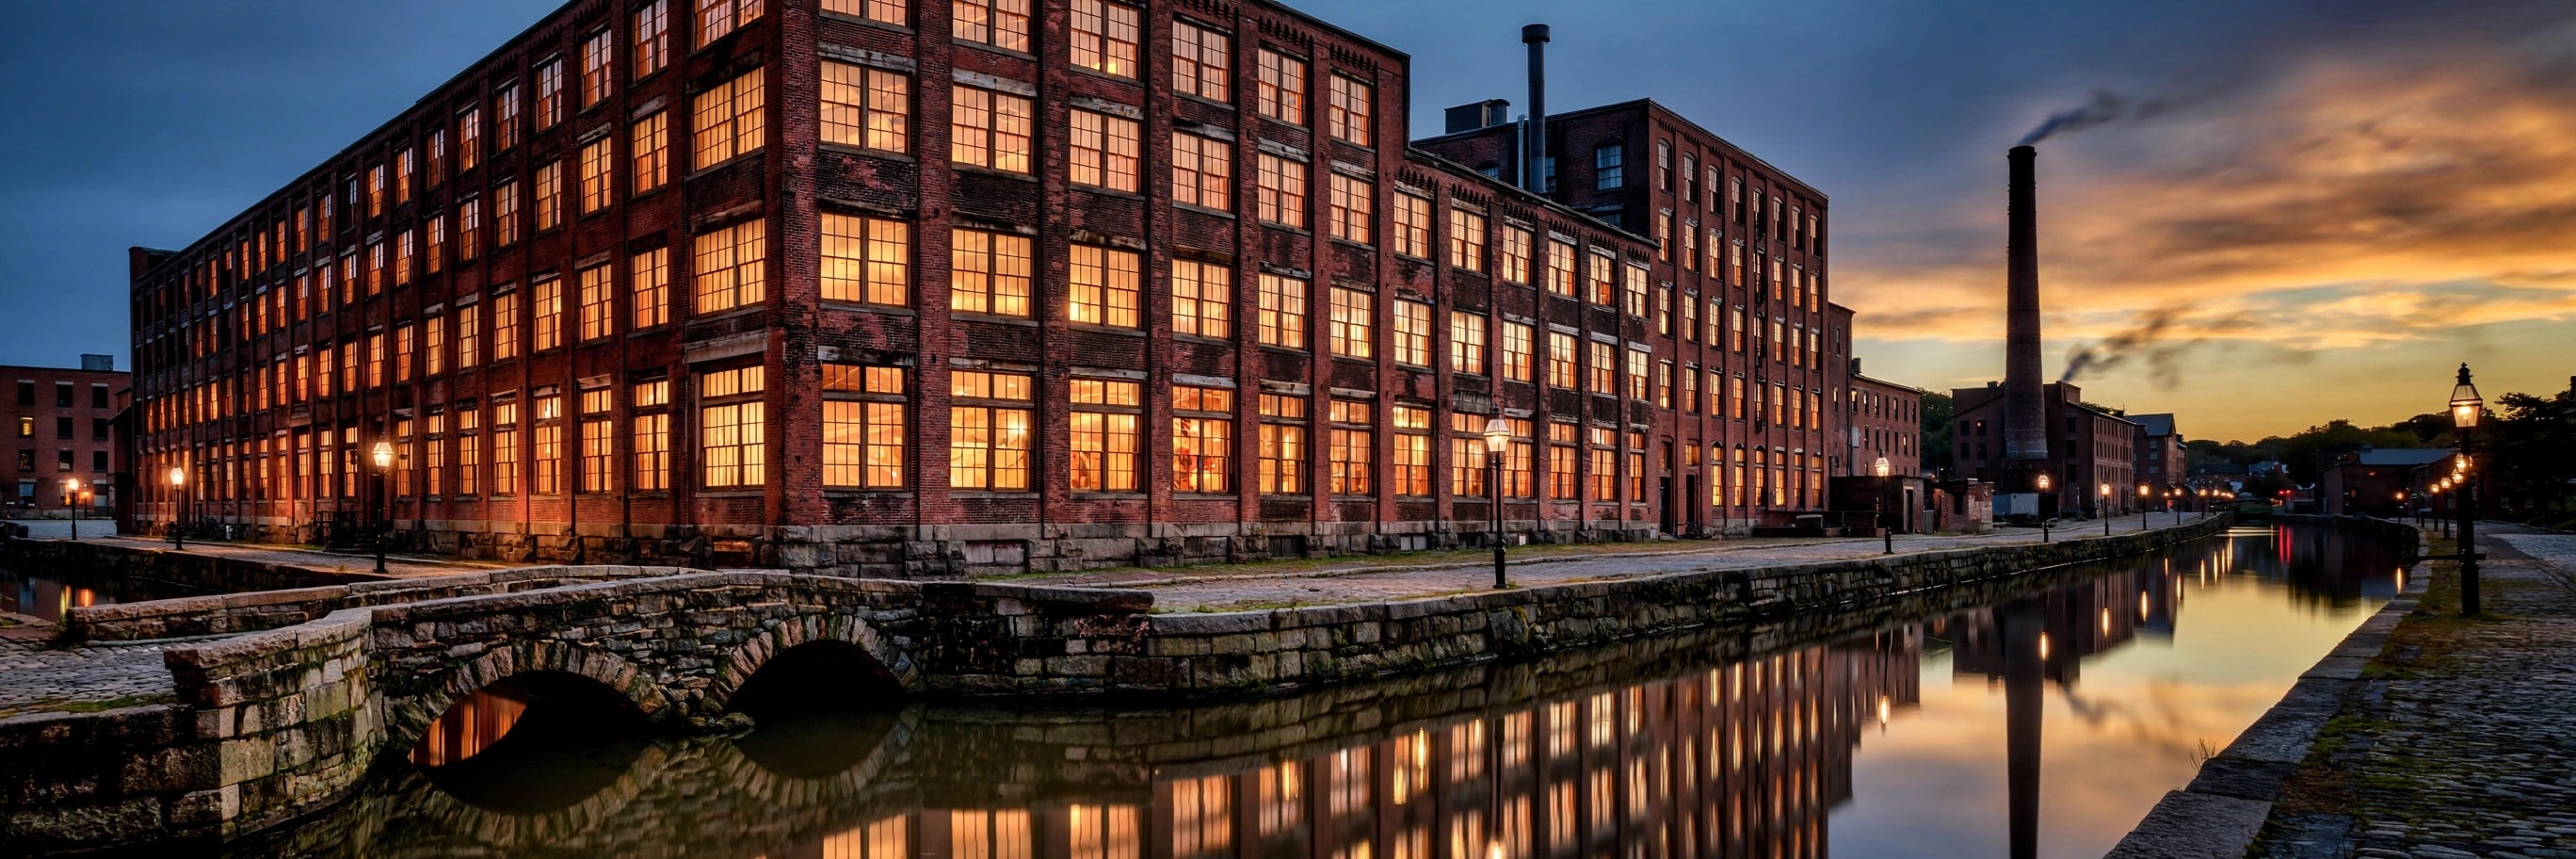
Buying a loft in Lowell, MA is one of the smartest value plays in Greater Boston real estate — authentic 19th-century mill character, walkable downtown, commuter rail to North Station, and prices around a third of Boston's. But mill lofts aren't like buying a suburban condo or a new-construction unit. The buildings are historic, the HOAs have their own cultures, and the due diligence matters more. If you're buying a loft in Lowell MA, here's what to know before you buy.
Buying a Loft in Lowell MA: Know Which Loft You're Getting
Downtown Lowell's loft inventory lives in a handful of converted mill buildings, and they differ more than you'd expect:
- Canal Place (200 Market Street): 1911 textile mill, hundreds of units across three buildings, one- to three-bedroom layouts, famously all-inclusive HOA covering heat, A/C, hot water, gas, water/sewer, elevator, maintenance, and insurance.
- Boott Cotton Mills (West Mill): 108 true-loft condos, studios to two-bedroom duplexes, river views, fitness center, roof deck, 12-hour concierge — the amenity leader.
- 491 Dutton Street: 65 luxury residences in an 1880 mill, former home of the American Textile History Museum — the design-and-history leader.
- 35 Riverwalk Way: riverfront luxury lofts near the UMass Lowell campus, quieter than the downtown core.
Tour at least two buildings before deciding. The difference between a canal-side building and a riverfront one — in light, noise, walkability, and HOA culture — is bigger than the price gap suggests.
The Mill-Loft Due Diligence Checklist
When you're buying a loft in Lowell, MA, standard condo due diligence gets an extra layer because the buildings are 100+ years old. Before your offer goes firm:
- HOA budget, reserves, and financials. Ask for the current budget, the reserve study, and the last two years of financials. Mill buildings need ongoing masonry, window, roof, and elevator work — a healthy reserve fund is the difference between a well-kept building and a surprise special assessment.
- Meeting minutes (12 months). You'll learn about planned projects, owner disputes, and how the building is really run. This is where assessment discussions surface first.
- Special assessments. Ask directly: are any planned or under discussion? Masonry repointing and window replacement on a mill building can run into the millions across a complex.
- Owner-occupancy ratio. Buildings with heavy rental concentrations can be harder to finance — some loan programs require minimum owner-occupancy — and harder to resell. This matters for your mortgage and your exit.
- Parking — in writing. Confirm exactly what comes with the unit: deeded space, assigned garage spot, monthly public-garage pass, or street parking. In downtown Lowell, a deeded or garage space is a genuine asset that affects resale.
- HOA rules. Pet policies, rental restrictions, renovation rules, and move-in/move-out policies vary widely. If you might rent the unit someday, confirm the building allows it.
- Master insurance vs. your HO-6. Understand what the association's master policy covers versus your individual unit policy. Mill buildings can carry higher master policy costs, which flow into the HOA fee.
- Pending litigation. Ask whether the association is involved in any lawsuits — construction-defect or developer disputes can complicate financing.
Financing: What Makes Mill Lofts Different
Here's the part that surprises buyers buying a loft in Lowell, MA: your loan approval depends on the building, not just on you.
- Condo approval matters. FHA and VA loans require the condominium project to be on the approved list. Not every mill conversion is approved — check your building against the HUD approved-condo list before you write an offer.
- Warrantability matters for conventional loans. Lenders look at owner-occupancy ratios, reserve funding, pending litigation, and single-entity ownership concentration. Buildings with strong HOAs sail through; troubled ones can kill a deal.
- MassHousing can help with the down payment. MassHousing, the state's housing finance agency, offers loan programs with down payment assistance options for eligible Massachusetts buyers — a real advantage for first-time buyers eyeing a $240,000–$270,000 loft, where the down payment hurdle is already low compared to Boston prices. Ask your lender about MassHousing options early in the process.
- Get a lender who knows condos. Mill conversions with all-inclusive HOAs can confuse underwriters who rarely see them. A lender experienced with Lowell condo buildings will know how to document HOA-covered utilities and fees correctly.
The True Monthly Cost
One-bedroom lofts in Lowell's mill buildings have been listed in the high $230s and two-bedrooms from the mid-$250s to around $270,000 — but the sticker price is only part of the monthly picture. Always calculate:
- Mortgage principal and interest
- Property taxes
- HOA fee (and what it replaces — in many Canal Place units, the fee covers heat, hot water, water/sewer, insurance, and more)
- Homeowner's insurance (HO-6 unit policy)
- Parking costs, if not included
A loft with a higher all-inclusive HOA can cost less per month than a cheaper unit where you're paying every utility separately. Run the full math before you compare listings.
Layout Quirks to Watch
Mill lofts are beautiful — and quirky. Ten-foot-plus ceilings, massive windows, exposed brick, and original beams come with trade-offs:
- Open floor plans can mean limited closet space and creative bedroom placement. Bring a tape measure.
- Oversized windows are gorgeous but can mean higher heating costs in winter and glare in summer — ask about the windows' age and insulation.
- Thick masonry walls mean excellent sound separation between units — a genuine perk of mill construction, since these buildings were engineered to hold tons of machinery.
- Storage varies enormously. Some buildings offer canal-level or basement storage cages; others offer almost none. If you have gear, bikes, or seasonal items, confirm storage before you commit.
Make Your Move With Confidence
Buying a loft in Lowell, MA rewards buyers who do the building homework: HOA health, parking, financing eligibility, and true monthly cost. Get those four right and you're buying one of the best values in Greater Boston — industrial-chic living minutes from the commuter rail at a fraction of city prices.
Call on Chris Doherty, Lowell's top-rated loft specialist. He knows the downtown mill buildings unit by unit — the HOA quirks, the parking realities, and which listings are the real values. Reach out to Doherty Properties for a no-pressure walkthrough of what's on the market today.
Check out this article next