
For a certain kind of buyer, the smartest first home in Greater Lowell isn't a condo, it's a multi-family. Buy one side, live in it, and let the other units help carry the mortgage. Multi-family homes, the two-to-four-unit buildings that line so many Merrimack Valley streets, are one of the best wealth-building tools in local real estate. Here's how they work and why they fit this region so well.
What Counts as a Multi-Family
A multi-family home is a single property with two to four separate living units. Two units is a duplex, three is a triple-decker, the classic New England building you'll spot all over Lowell, Lawrence, and Haverhill, and four is a four-unit. Each unit has its own kitchen and bath, and you can live in one while renting the others. Properties with five or more units cross into commercial territory, so two-to-four-unit buildings are the sweet spot for residential buyers.
The House-Hack Play
The core strategy is simple: your tenants' rent offsets your housing cost. Live in one unit of a triple-decker and the other two rents can cover a large share of your monthly payment, sometimes most of it. Owner-occupant buyers also get access to residential financing on up to four units, including low-down-payment programs, which keeps the entry cost far lower than buying an investment property as a non-occupant. It's the closest thing to having someone else help pay your mortgage while you build equity.
Why the Merrimack Valley Is Multi-Family Country
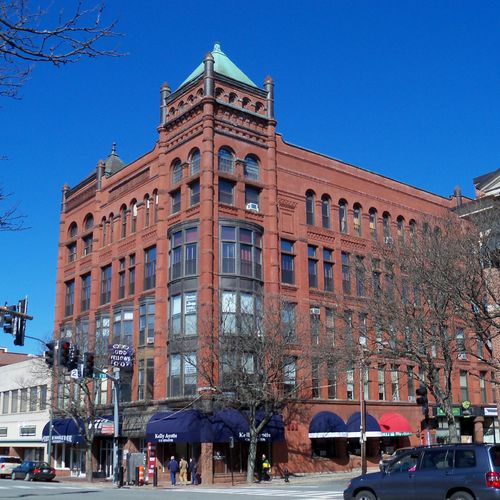
Two-to-four-unit buildings are woven into the fabric of the Merrimack Valley. Mill cities like Lowell and Lawrence were built on worker housing, and their streets are lined with sturdy two- and three-family buildings that have been cash-flowing for a century. Haverhill offers similar stock with a slightly different price profile. Southern New Hampshire, Nashua included, has its own inventory of multi-families for buyers chasing the tax advantages. Rental demand across the region runs deep thanks to the workforce, the colleges, and the Boston commuter spillover, which keeps vacancy risk low for well-kept units.
What to Watch Before You Buy
These homes reward due diligence. Get the full picture on each unit's condition, roofs, heating systems, and electrical matter more when they're multiplied across units. Ask about current leases, rent rolls, and whether tenants are month-to-month. In Massachusetts, lead paint disclosure rules apply to pre-1978 homes, and many two- and three-family buildings in the Valley fall in that window, your agent should walk you through compliance. And run the numbers conservatively: budget for vacancies and repairs, not just the best-case rent.
Multi-Family vs. Condo: The Honest Comparison
Condos give you low maintenance and amenities; a multi-family gives you control and income. With a two-to-four-unit building, there are no condo fees and no HOA telling you what color to paint, but when the furnace dies, it's your furnace. The tradeoff favors buyers who are handy, or who plan to hire a property manager once the building is stabilized. Over time, the equity-building math usually wins for buyers willing to be landlords.
Best for: First-time buyers who want to offset their mortgage, investors starting with an owner-occupied purchase, and anyone comfortable being a landlord. Price context: Pricing varies widely by unit count, condition, and town, reach out for current figures. Vibe: The classic Merrimack Valley wealth-builder, hiding in plain sight on every mill-city street.
Start With the Numbers
The right purchase starts with honest math: purchase price, realistic rents, taxes, insurance, and a repair reserve, all stress-tested before you offer. Chris Doherty closes 100+ transactions a year across Greater Lowell as one of the region's top-producing agents, and the Doherty Properties team knows the multi-family streets of Lowell, Lawrence, and Haverhill unit by unit. Reach out, we'll help you find a home where the numbers actually work.
Check out this article next